GAP insurance Ireland: best providers compared (2026)
GAP insurance Ireland: best providers compared (2026) ! Irish man reviewing GAP insurance papers at kitchen table Which GAP insurance providers in Ireland are worth your money?
Which GAP insurance providers in Ireland are worth your money?
GAP insurance in Ireland bridges the shortfall between what your motor insurer pays out after a total loss and either the original invoice price or your outstanding finance balance. If your car is written off or stolen, standard comprehensive cover pays current market value only. That figure can fall thousands of euros short of what you actually owe or paid. GAP cover closes that gap.
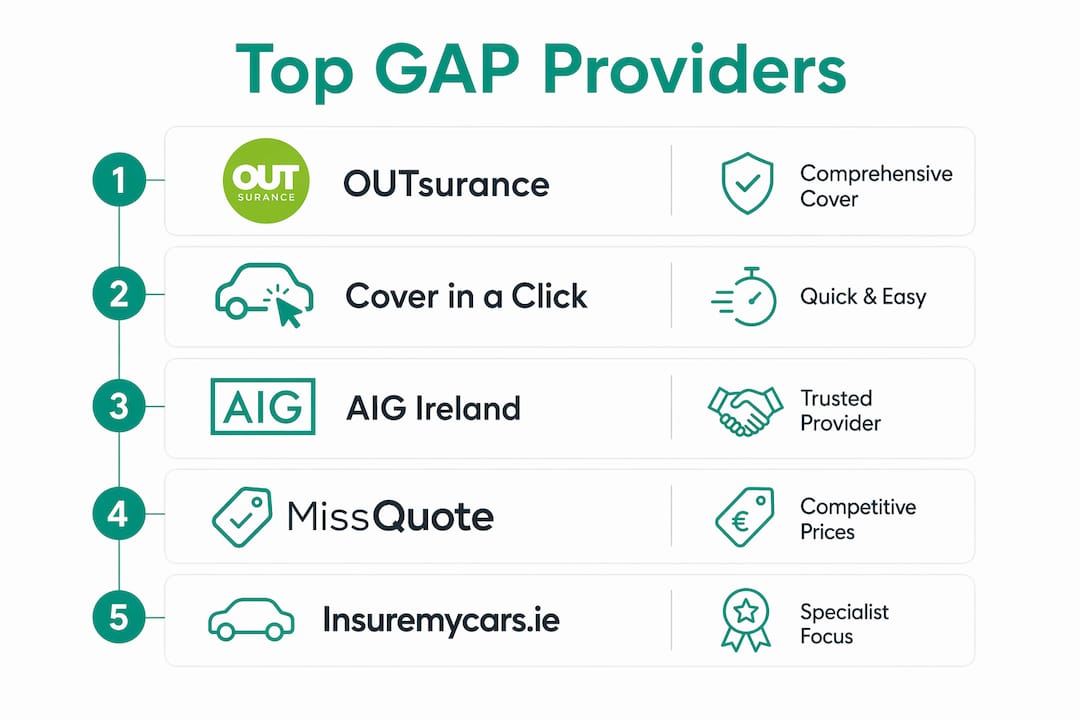
The five providers below are actively available to Irish buyers. They are not all pure GAP specialists, but each offers relevant cover or sits in the broader insurance market where GAP products are sourced.
| Provider | GAP cover type | Key benefit | Special feature | Rating |
|---|---|---|---|---|
| OUTsurance Ireland | Car insurance with GAP-adjacent cover | Value-for-money premiums | cashback after a claim-free period | 4.9★ (thousands of reviews) |
| Cover in a Click | Comparison broker, multiple quotes | Flexible payment options | online discount | 4.6★ (hundreds of reviews) |
| AIG Ireland | Tailored personal and business cover | a notable no claims discount | Online policy management via MyAIG | 3.3★ (almost two hundred reviews) |
| [MissQuote | Car Insurance Broker](https://missquote.ie/) | Women’s car insurance brokerage | Safe driver discounts | online saving, stepback bonus protection |
| Insuremycars.ie | Multi-quote comparison, multiple quotes | Named driver and no-claims discounts | Electric vehicle and company car cover | — |
OUTsurance Ireland stands out for buyers who want a direct Irish insurer with a clear loyalty incentive. The 10% cashback on premiums after three consecutive claim-free years is a genuine financial return, not just a marketing promise. Their underwriting is local, and their claims process is built around Irish regulatory standards.
Cover in a Click suits drivers who want to compare the market quickly. Comparing 15 car insurance quotes in one place, combined with an online discount, makes it a practical starting point for anyone buying a new or used car and wanting to bundle their search.
AIG Ireland is the strongest option for business buyers and fleet operators. Their tailored approach to both personal and commercial motor insurance, backed by a global insurer, means policies can be structured around specific fleet or leasing arrangements. The up to 65% no claims discount for six or more claim-free years rewards long-term safe driving.
MissQuote is a specialist broker for female drivers, offering benefits that go beyond price: breakdown assistance, stepback bonus protection, and windscreen cover are built into their proposition. The online saving applies at point of purchase.
Insuremycars.ie covers the broadest range of driver types, including named drivers, electric vehicle owners, and company car users. Their flexible payment structure, either upfront or by instalments, suits buyers managing tight monthly budgets.
How to choose the right GAP insurance in Ireland
The single most important decision is matching the cover type to your actual financial exposure. There are two core types:
- Return to Invoice (RTI): pays the difference between your motor insurer’s settlement and the original purchase price you paid for the vehicle.
- Finance GAP: pays the difference between the settlement and the outstanding balance on your finance agreement.
If you bought outright, RTI is the relevant product. If you are financing, Finance GAP protects you from owing more than the car is worth after a write-off. Some policies, such as the Return to Invoice Combined product offered by providers like Car Protect, combine both into a single policy.
Key criteria to compare before you buy:
- Coverage basis: does the policy pay to invoice price, finance balance, or replacement value?
- Policy duration: most Irish GAP policies run for several years duration as a once-off payment.
- Claim limit: the maximum payout under many policies is a substantial maximum claim limit, including up to a portion of your motor excess.
- Exclusions: delivery charges, road fund licence, fuel, and paintwork protection kits are typically excluded from the net invoice calculation.
- Eligibility: most policies require the vehicle to be under a certain age and under a maximum mileage limit at purchase.
- Claims process: you must contact the GAP insurer before accepting your motor insurer’s settlement offer.
Red flags to watch for:
- Policies that do not clearly define “net invoice price” in the schedule.
- Cover sold after the 90-day ownership window has passed (most policies require purchase within a limited window after ownership start of taking ownership).
- Negative equity excluded without an explicit add-on option.
- No mention of territorial limits (standard Irish policies cover the Republic of Ireland, Great Britain, the Isle of Man, the Channel Islands, and EU member states).
Questions to ask any provider before buying:
- Does this policy cover my finance settlement or my original invoice price?
- What is the maximum claim limit, and does it include my motor excess?
- Are optional extras and dealer-fitted accessories included?
- What documentation do I need to submit a claim?
Pro Tip: Buy GAP cover as close to vehicle purchase as possible. Depreciation is steepest in the first several years duration, and your finance balance is highest at the start. Waiting even a few months reduces the cover’s value without reducing your financial risk.
Understanding GAP insurance in Ireland: what it covers and how it works
GAP insurance, or Guaranteed Asset Protection, exists because comprehensive motor insurance pays market value at the time of loss, not what you paid. A car that cost a typical purchase price twelve months ago may be valued at a depreciated value by your insurer after a write-off. If you still owe an outstanding finance balance on finance, you face a €5,000 shortfall. GAP cover pays that difference.
For a valid claim, two conditions must be met: you must hold a comprehensive motor insurance policy with an Irish-authorised insurer, and your vehicle must be declared a total loss within the policy period and territorial limits. Partial losses are not covered.
Core coverage elements:
- Pays the gap between motor insurer settlement and invoice price or finance balance (whichever is greater under combined policies).
- Covers up to a substantial maximum claim limit per claim under standard Irish policies, including up to a portion of your motor excess.
- Available for new and used cars valued under a maximum vehicle value, under a certain age, and with under a maximum mileage limit.
- Policy duration is typically several years duration, purchased as a once-off payment.
- Territorial cover includes Ireland, Great Britain, the Isle of Man, the Channel Islands, and EU member states.
What is not covered:
- Road fund licence, delivery charges, fuel, and cosmetic protection kits.
- Factory or dealer-fitted extras exceeding a limit on optional extras in total.
- Negative equity (unless purchased as a specific add-on).
- VAT on commercial vehicles.
- Total losses outside the territorial limits.
Claims process in brief:
- Contact the GAP insurer within a deadline for claims contact of the total loss event.
- Submit the original purchase invoice, your motor insurer’s final settlement offer, and a completed claims form.
- Do not accept your motor insurer’s valuation before speaking to your GAP insurer. The GAP insurer may negotiate the total loss valuation on your behalf.
Insider knowledge on the Irish GAP insurance market
Reading the policy schedule carefully is not optional. The term “invoice price” sounds straightforward, but manufacturer and dealer policies routinely exclude motor tax, delivery fees, insurance premiums, and warranty costs from the net invoice calculation. The figure used for your claim may be lower than the total you paid on the day.
Business fleet buyers face a different set of considerations. The right product for a private buyer is not necessarily right for a company car or leased vehicle. Fleet operators need to match the GAP product to how depreciation and finance settlements interact within their specific lease or hire purchase agreement. Finance GAP is often more appropriate for lessees than Return to Invoice, because the outstanding finance balance is the real exposure.
Practical insider tips:
- Always read the definitions section of the policy document, not just the product name. “Return to Invoice” means different things across different providers.
- Manufacturer-backed programmes from brands like Volkswagen and Audi offer GAP cover through their finance arms, but third-party providers often offer comparable cover at lower cost.
- Policy transparency and local underwriting are stronger trust signals than marketing claims. A policy regulated by the Central Bank of Ireland carries a clear regulatory framework for disputes.
- GAP policies are sometimes transferable to a new owner, subject to underwriter agreement, which can add resale value.
- Timing matters more than most buyers realise. Buying GAP on the day of vehicle purchase, or within the 90-day window, gives you the maximum protection during the period of highest depreciation risk.
Buying a car in Ireland? Ecosteer lists vehicles alongside the costs
If you are searching for a car to insure, Ecosteer offers a faster route to finding the right vehicle before you sort the cover. Rather than browsing multiple dealer sites, you can search cars for sale across Ireland in one place, filtering by county, price, fuel type, and mileage.
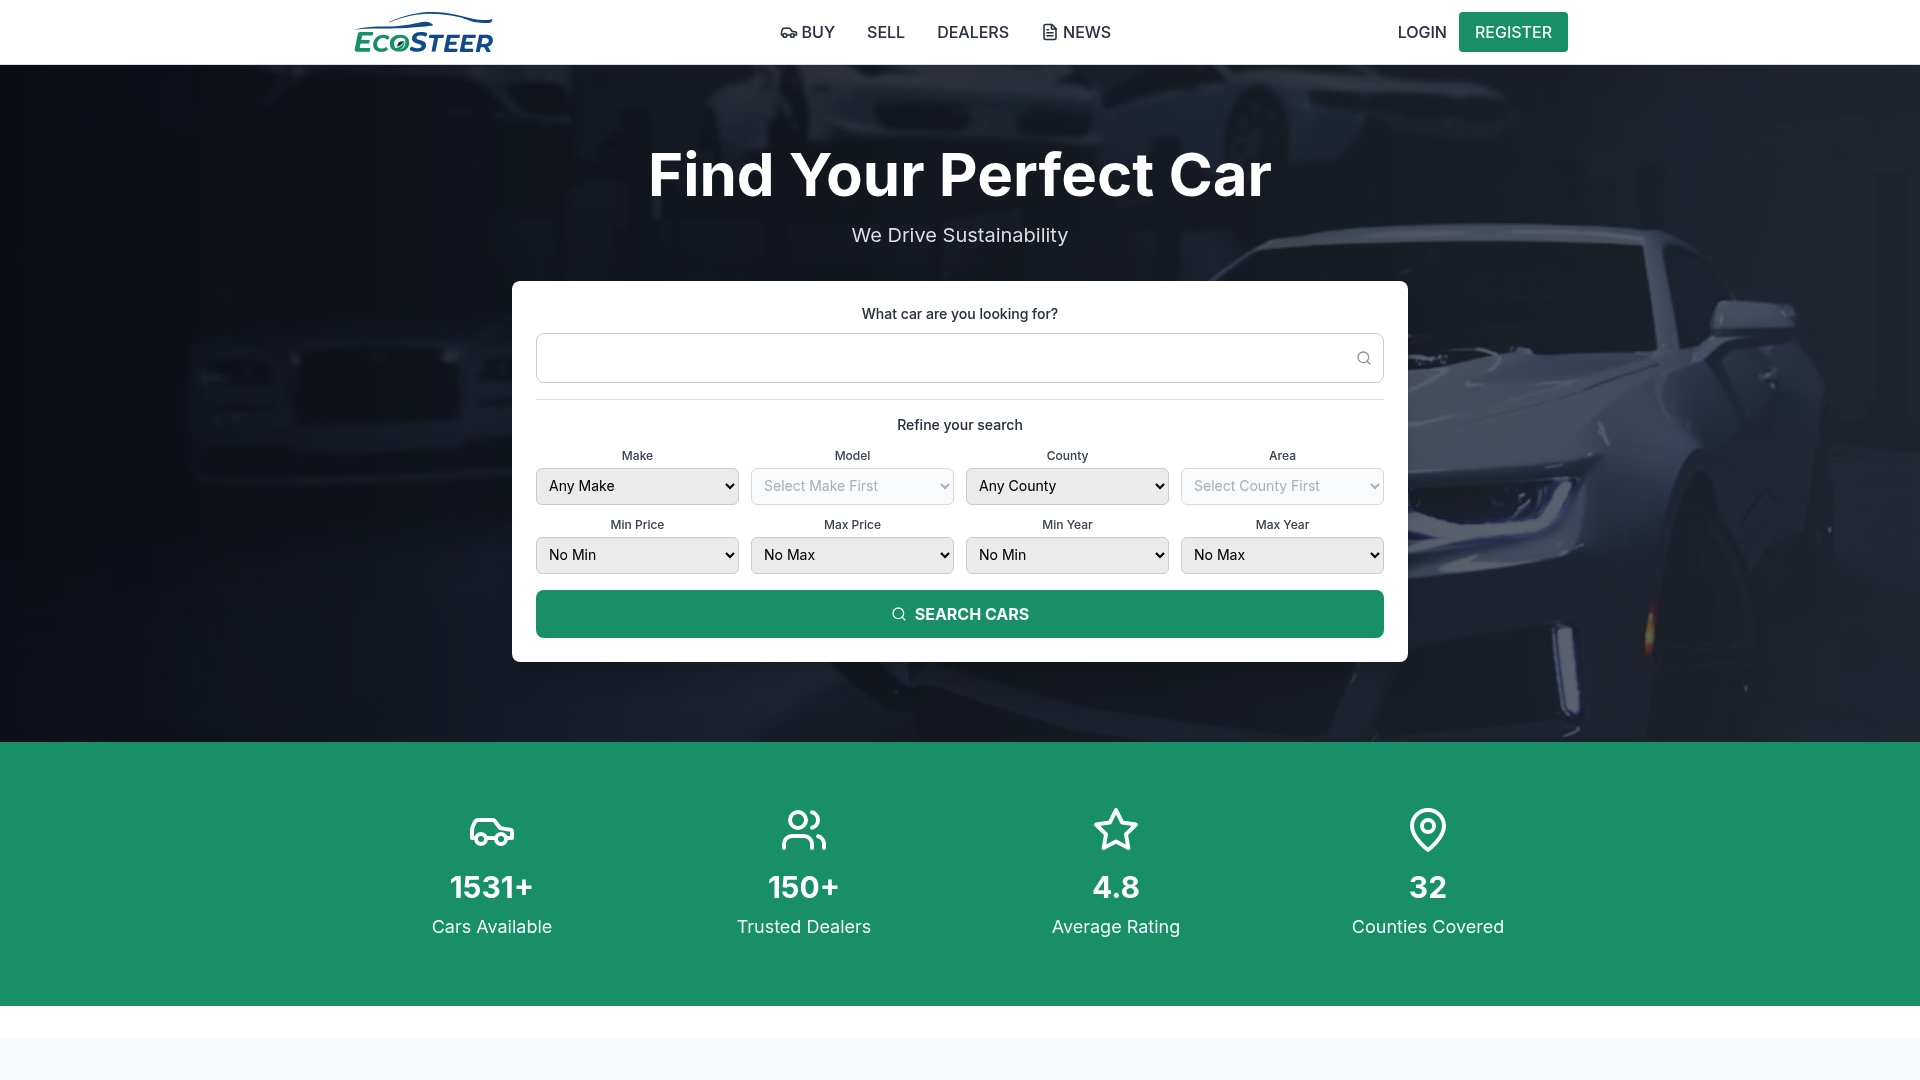
GAP insurance decisions start with the vehicle purchase itself. Knowing the invoice price, the finance terms, and the vehicle age at purchase are all inputs that determine which GAP product fits. Ecosteer’s listings give you that information upfront, alongside tools to find a dealer near you. It is a practical first step before you compare cover.
Key takeaways
GAP insurance in Ireland is a once-off payment product that covers the shortfall between a motor insurer’s total loss payout and either the original invoice price or the outstanding finance balance, typically for several years duration.
| Point | Details |
|---|---|
| Match cover to exposure | Choose Return to Invoice for outright purchases; Finance GAP for financed vehicles. |
| Buy within a limited window after ownership start | Most Irish GAP policies require purchase within a limited window after ownership start of taking vehicle ownership. |
| Check exclusions carefully | Delivery charges, road tax, and negative equity are typically excluded from net invoice calculations. |
| Contact GAP insurer first | Before accepting your motor insurer’s settlement, notify your GAP insurer to protect your claim. |
| Ecosteer for vehicle search | Ecosteer lists used cars across Ireland with full details, helping you establish the invoice price before choosing a GAP product. |
Recommended
Ecosteer Editorial
Author